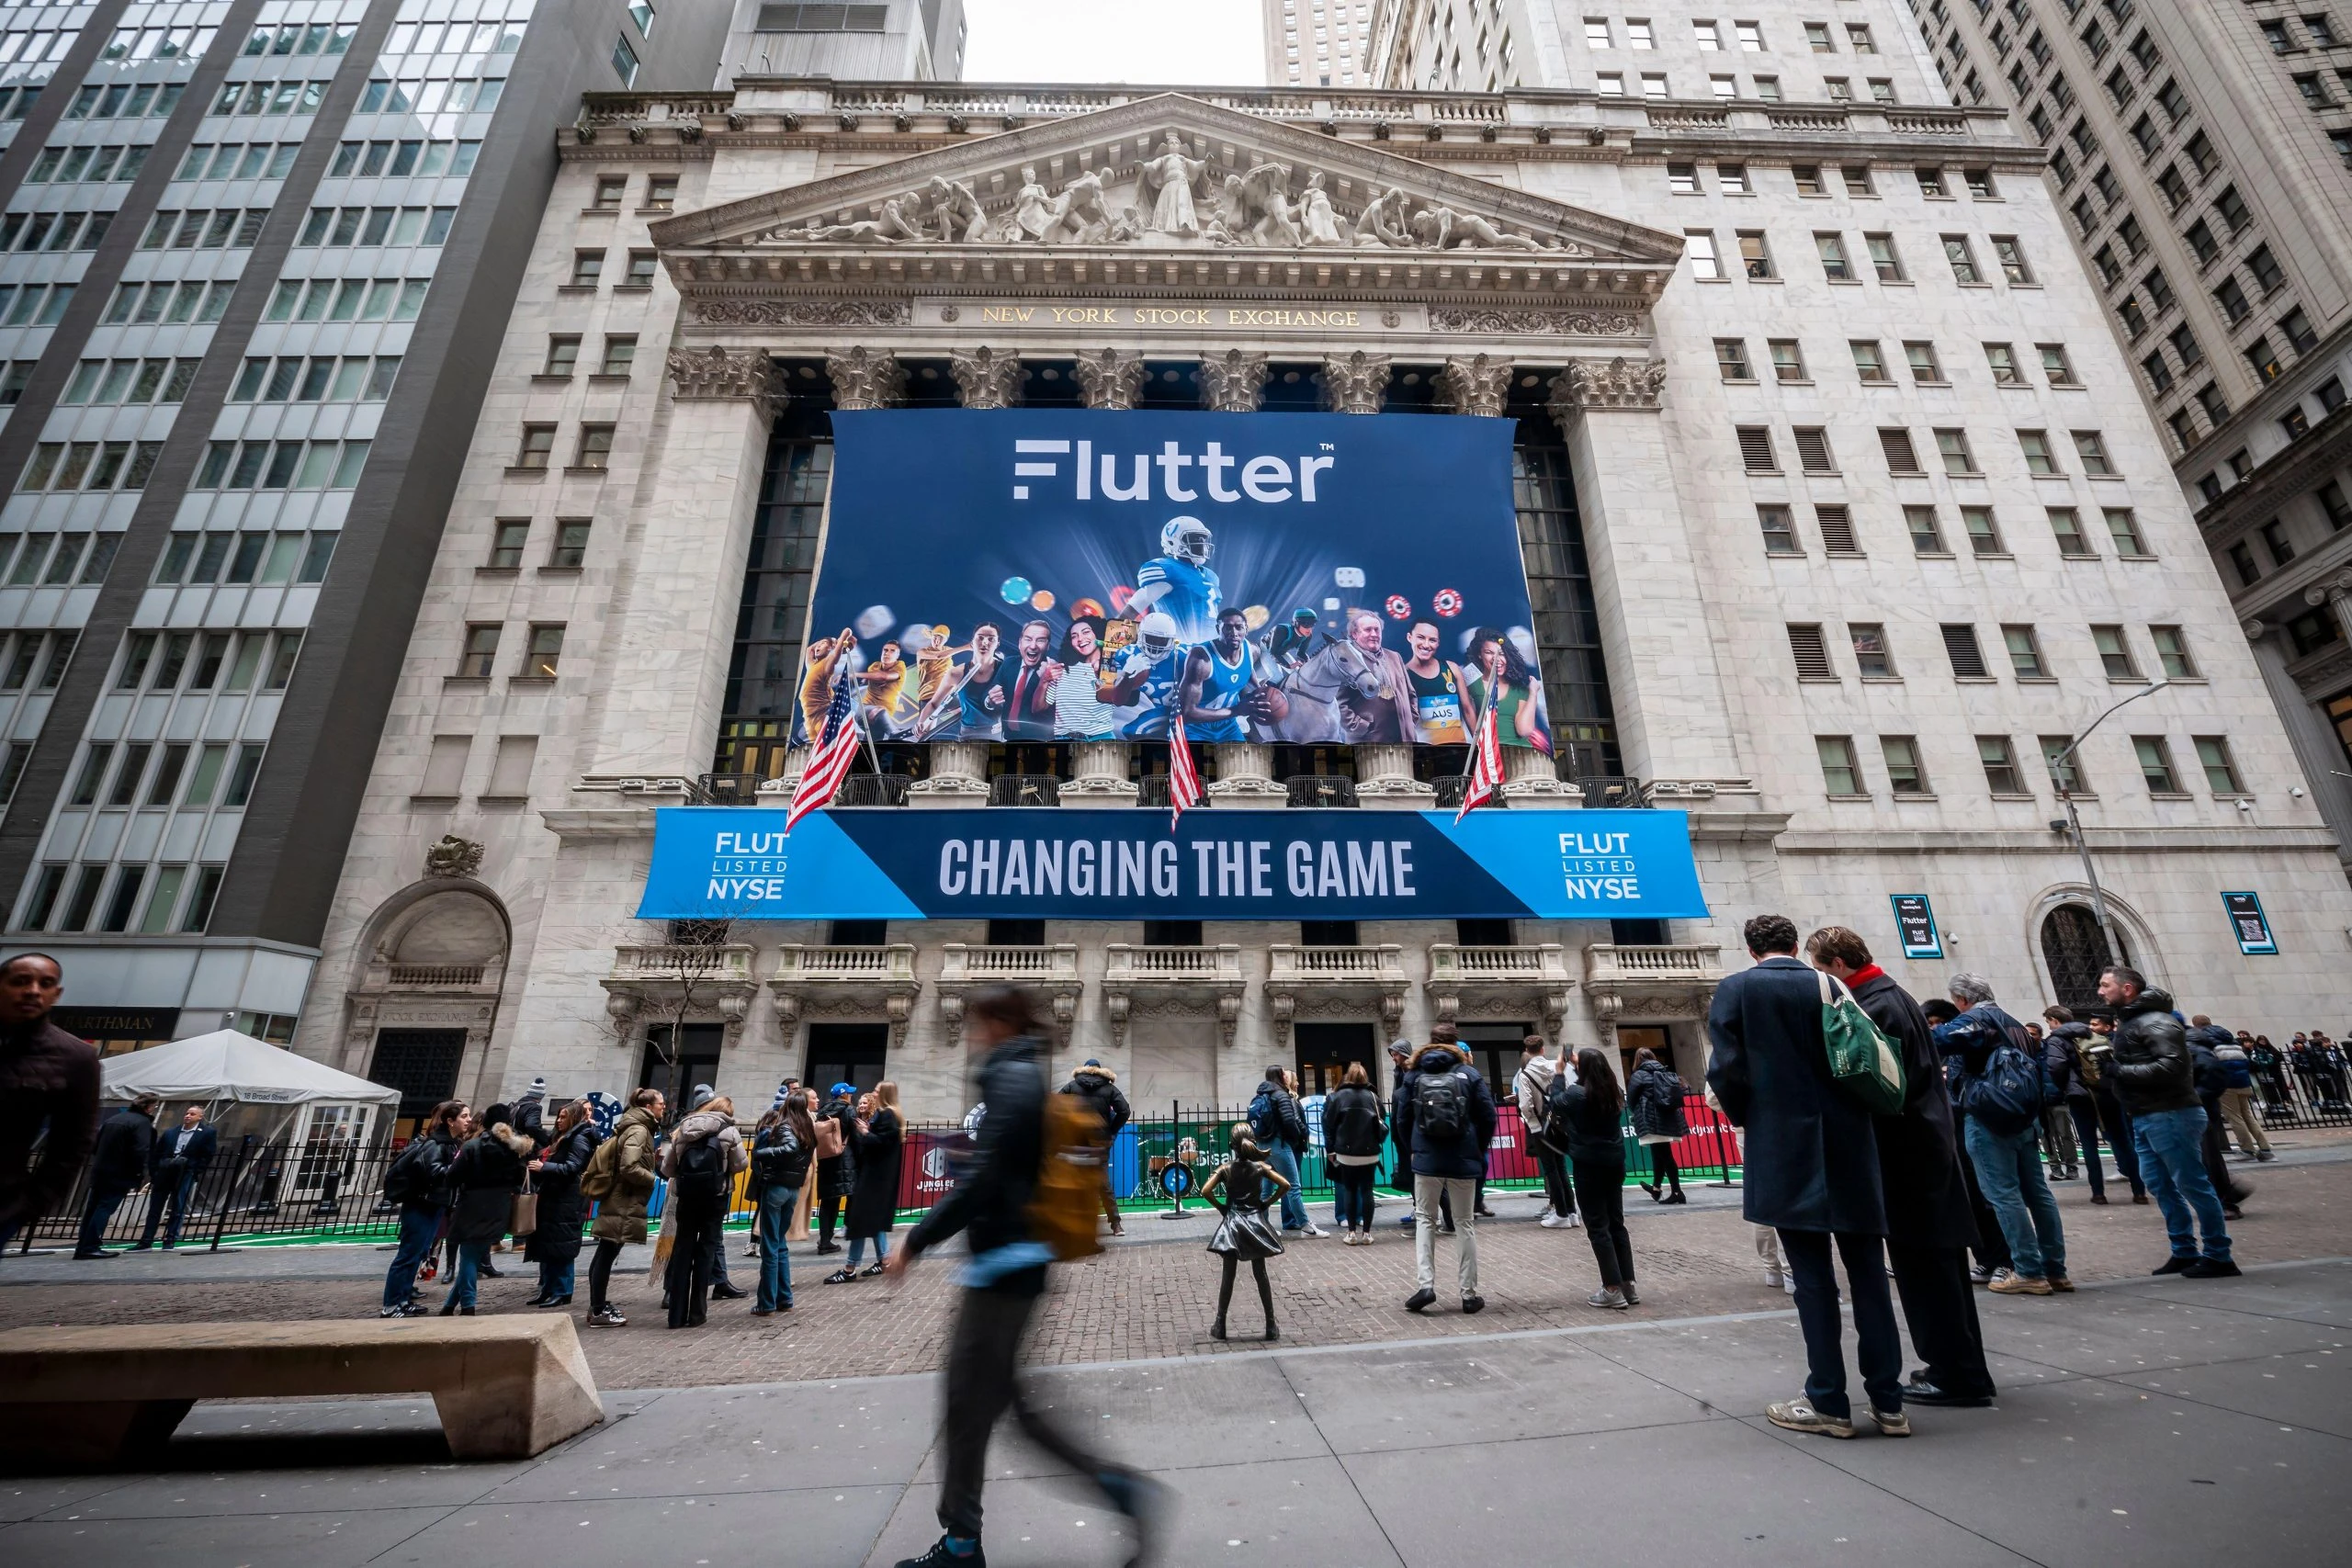
At 8am on 3 August, Flutter Entertainment’s shares will quietly stop trading in London, ending a listed lineage that began with Paddy Power’s float in December 2000. The company blamed thin trading volumes and the cost and regulatory burden of a dual listing; from August, the world’s largest online gambling group will trade solely in New York, where its primary listing has sat since May 2024.
Flutter leaves the UK at a challenging moment: the shares are down nearly half this year and around 60% over 12 months, cutting a market value that topped $50 billion last summer to around $19 billion.
It is tempting to read those two facts together – the move to Wall Street and the collapse in the share price – as cause and effect, another warning about a company that chased higher valuations in America and found American volatility instead.
But perhaps the real question hanging over Flutter is whether the US market it staked everything on still has the profile investors were promised when the company packed for New York: continued legalisation, a settled duopoly and years of profitable growth. On all three counts, the picture has blurred.
The listing is not the issue
Start by dealing with the listing question. “There’s no reason to think any of this would be different if they were still listed in London,” says a senior US-based financial stock analyst that iGB has spoken to. “I don’t know how many investors would only invest in London and not in the US. The pool of capital is bigger in the US.”
Earlier examples cut both ways, he notes. Light & Wonder scrapped its dual listing for an ASX-only listing after its valuation fell, while Aristocrat is valued more highly partly because Australia’s smaller stock market has few high-quality listed companies.
Deutsche Bank, cited in a recent Scott Longley column, drew the same lesson from Flutter itself: a US listing “does not automatically deliver favourable outcomes”, and deeper liquidity can amplify bad news through heavier trading and easier shorting.
Ben Robinson, managing partner at Corfai, is similarly unsentimental about Flutter’s exit. “It’s hard to argue with the mechanics,” he says. “The primary listing moved to New York in 2024, London had become a shrinking secondary line and the volumes no longer justified the cost. The real loss is marginal and symbolic. Some UK funds with LSE-only mandates become forced sellers, and a company built on Paddy Power and Betfair has cut its last formal tie to its home market.” Whether that matters, he adds, “depends on whether Flutter ever needs London again. My instinct is it won’t.”
Chad Beynon, senior gaming, lodging and theatres analyst at Macquarie, sees no reason for regret either. “The US has the largest and most liquid equity market in the world,” he says, pointing to institutional depth, retail participation and a lower cost of capital for the group. The postcode, all three agree in effect, is irrelevant. What has driven the stock is the story.
Rethinking the US opportunity
And the story has changed. “Until the prediction-market shake-up, yes,” says Robinson, asked whether the American pivot delivered what investors expected. “FanDuel built a 39% share of US sportsbook and the move stateside looked like the trade of the decade. Since then the stock has lost around 60% in a year, with the market increasingly questioning a growth story built partly on new states opening. Kalshi and Polymarket can now reach customers in California, Texas and Florida without waiting for conventional sports-betting licences, and that opportunity has been repriced.”
The numbers behind the repricing are stark. Robinson notes that Kalshi generated more than $30 billion of volume in June “while operating across markets that conventional sportsbooks still cannot fully access. That reduces the scarcity value of future state licences.”
Growth in regulated states has matured at the same time, he says: “That looks more like a structural re-rating than a blip.”
Beynon frames the same wound from the equity side: in states where betting is legal, prediction markets’ financial impact “has been minimal” – but “investors are discounting the future growth of the US legal market, or at least the duopoly between DraftKings and FanDuel”.
Investors are no longer just cutting their short-term expectations. They are asking whether the two-company market that drove high valuations can last, and whether California and Texas will still be open to opportunities when they arrive.
The push for legalisation, meanwhile, has slowed. The hypothesis, as the US analyst puts it, was that states would rather tax legal sportsbooks than watch money flow to federally regulated contracts beyond their reach. “But it’s been slow. If anything, you’ve seen tax increases. North Carolina has increased taxes, and now Ohio has introduced a bill to end sports betting, which is pretty bizarre when you think about it. You’d still have prediction markets.”
The business carrying the weight
Is Flutter, then, over-reliant on America? “The reliance is real, but the picture is shifting,” says Robinson. The US, roughly 40% of group revenue, “grew just 6% in Q1, with handle down 9% and US EBITDA down 26%. International grew 27%, although that was driven largely by Snai and Betnacional and was broadly flat organically. For now, the international business everyone stopped talking about is doing the heavy lifting.”
Amy Howe’s abrupt exit from FanDuel in May fits the pattern: “The FanDuel leadership change suggests the board wanted tighter oversight too,” says Robinson.
That puts pressure on the division Flutter spent two years reducing its focus on: internationally, “whether growth holds once Snai and Betnacional annualise”, in the UK, “the first full quarter under 40% RGD”, after remote gaming duty nearly doubled in April. Flutter estimates a $320 million pre-mitigation EBITDA hit in 2026, rising to $540 million in 2027.
“The key question is whether mitigation comes from genuine cost savings or lower marketing, which may protect margins now but weaken future growth.”
Higher UK taxes have historically squeezed out smaller rivals – as seen with the consolidation around Evoke and Bally’s – and handed Flutter share. The US analyst says the question is whether that playbook still runs.
Flutter’s two paths forward
How does the US market move forward? The US analyst outlines two paths: “Either Flutter needs to start taking share in prediction markets – perhaps as a market maker rather than through an exchange – or investors need confidence that prediction markets won’t be a serious, long-term headwind.”
Flutter’s late-2025 launch of FanDuel Predicts, via an exchange partnership with CME Group, has had a quieter start than DraftKings’ product. Making money from the risk, not just providing the platform, may be the key to making prediction markets profitable rather than just defensive.
Failing that, the industry waits on the courts, where the outcome remains uncertain. Nevada has successfully restricted Kalshi, Robinson notes, but the Third Circuit ruled in its favour against New Jersey, and “there is no binding nationwide answer today”. The balance is not even either: “Nevada matters less commercially than California, Texas and Florida, where the central threat remains intact.”
The US analyst expects everything to roll up to the Supreme Court, with no final answer “before late 2027 at the earliest, and more likely sometime in the first half of 2028”. Until then, “there’s a risk that these stocks trade sideways”.
There is also a concern rarely discussed: if courts eventually block sports prediction contracts, companies that invested in them “will certainly hope they’re not punished by state legislators for having been involved”, he says. “If regulators decide companies were on the wrong side of the issue, they may not be welcomed back quite so easily.”
Will New York deliver Flutter’s promised gains?
None of this has reduced the transatlantic allure. Allwyn – newly consolidated with Greece’s OPAP, listed in Athens and buying into the US via PrizePicks – is weighing a secondary listing in London or New York.
The US analyst reads it as “a bit of an arbitrage play” adding, “you’re becoming a much larger player in a smaller market – a big fish in a smaller pond”.
Beynon rejects the idea that listings compete at all: “We don’t view listed gaming company investments as a ‘zero-sum game’.” And the US analyst insists Flutter’s destination was right: “I still think the US is the gold standard for capital markets.”
Robinson’s verdict is subtler. “Premature is the instinct, but the maths probably supports it,” he says of the full exit – although he detects “an element of message in the timing too: London doubled ...
8月3日上午8点,Flutter Entertainment的股票将悄然停止在伦敦交易,终结了一段始于2000年12月Paddy Power上市的上市传承。该公司将原因归咎于交易量稀薄以及双重上市的成本和监管负担;从8月起,这家全球最大的在线博彩集团将仅在纽约交易,其第一上市地自2024年5月起便一直在纽约。
Flutter离开英国之际正值一个充满挑战的时刻:其股价今年已下跌近一半,过去12个月下跌约60%,市值从去年夏天超过500亿美元缩水至约190亿美元。
人们很容易将这两个事实——迁往华尔街和股价暴跌——放在一起解读为因果关系,视为对一家追逐美国更高估值却遭遇美国式波动的公司的又一警告。
但或许悬在Flutter头上的真正问题是,它押上一切的美国市场是否仍具备该公司当初收拾行囊奔赴纽约时向投资者承诺的特征:持续的合法化、稳定的双头垄断以及多年的盈利增长。在这三点上,前景都已变得模糊。
上市并非问题所在
先从上市问题说起。“没有理由认为如果他们仍在伦敦上市,这一切会有所不同,”一位接受iGB采访的驻美资深金融股票分析师表示。“我不知道有多少投资者只投资伦敦而不投资美国。美国的资金池更大。”
他指出,此前的案例各有正反两面。Light & Wonder在估值下跌后放弃了双重上市,仅在澳交所上市,而Aristocrat估值较高,部分原因是澳大利亚较小的股市中高质量上市公司寥寥无几。
德意志银行在Scott Longley最近的专栏中被引用,从Flutter自身得出了同样的教训:美国上市“并不会自动带来有利结果”,更深的流动性可能通过更重的交易和更容易的做空来放大坏消息。
Corfai管理合伙人Ben Robinson对Flutter的退出同样不带感情色彩。“从机制上讲很难反驳,”他说。“第一上市地于2024年迁至纽约,伦敦已沦为不断萎缩的第二上市地,交易量已不再能证明成本的合理性。真正的损失是边际性的和象征性的。一些仅限伦交所授权的英国基金被迫成为卖方,而一家建立在Paddy Power和Betfair基础上的公司已切断了与本土市场的最后一条正式纽带。”他补充说,这是否重要,“取决于Flutter是否还需要伦敦。我的直觉是不会。”
麦格理高级博彩、住宿及剧院分析师Chad Beynon同样认为没有理由后悔。“美国拥有世界上最大、流动性最强的股票市场,”他说,并指出其机构深度、散户参与度以及该集团更低的资本成本。三人都认为,上市地点实际上无关紧要。推动股价的是故事。
重新审视美国机遇
而故事已经改变。当被问及美国转向是否带来了投资者所期望的结果时,Robinson说:“在预测市场巨变之前,是的。FanDuel建立了39%的美国体育博彩市场份额,转向美国看起来像是十年一遇的交易。自那以后,该股一年内下跌约60%,市场越来越质疑一个部分建立在新州开放基础上的增长故事。Kalshi和Polymarket现在可以在加利福尼亚、德克萨斯和佛罗里达接触客户,而无需等待传统体育博彩牌照,这一机遇已被重新定价。”
重新定价背后的数字是惊人的。Robinson指出,Kalshi在6月产生了超过300亿美元的交易量,“同时在传统体育博彩公司仍无法完全进入的市场中运营。这降低了未来州牌照的稀缺价值。”
他说,受监管州的增长同时也已成熟:“这看起来更像是结构性重估,而非暂时波动。”
Beynon从股票角度描述了同样的创伤:在博彩合法的州,预测市场的财务影响“微乎其微”——但“投资者正在折价美国合法市场的未来增长,或者至少是DraftKings和FanDuel之间的双头垄断”。
投资者不再只是削减短期预期。他们在质疑,推动高估值的双公司市场能否持续,以及加利福尼亚和德克萨斯在机遇到来时是否仍会敞开大门。
与此同时,合法化的推进已经放缓。正如那位美国分析师所说,此前的假设是各州宁愿对合法体育博彩征税,也不愿看着资金流向其无法触及的联邦监管合约。“但进展缓慢。如果说有什么变化,那就是你看到了增税。北卡罗来纳州提高了税收,现在俄亥俄州提出了一项终止体育博彩的法案,想想真是相当奇怪。你仍然会有预测市场。”
承担重任的业务
那么,Flutter是否过度依赖美国?“依赖是真实的,但情况正在变化,”Robinson说。美国约占集团收入的40%,“第一季度仅增长6%,投注额下降9%,美国EBITDA下降26%。国际业务增长27%,尽管这主要由Snai和Betnacional推动,有机增长基本持平。目前,所有人都不再谈论的国际业务正在挑大梁。”
Amy Howe于5月突然离开FanDuel符合这一模式:“FanDuel的领导层变动表明董事会也希望加强监督,”Robinson说。
这给Flutter花了两年时间减少关注的部门带来了压力:在国际上,“一旦Snai和Betnacional进入同比基数,增长能否维持”;在英国,“40%远程博彩税下的第一个完整季度”,此前远程博彩税在4月几乎翻倍。Flutter估计2026年税前缓解前EBITDA将受到3.2亿美元冲击,2027年将升至5.4亿美元。
“关键问题是缓解措施是来自真正的成本节约还是削减营销,后者可能现在保护利润率,但会削弱未来增长。”
英国增税历来会挤出较小的竞争对手——正如Evoke和Bally’s周围的整合所显示的那样——并将市场份额让给Flutter。那位美国分析师说,问题是这套打法是否仍然有效。
Flutter前进的两条路径
美国市场如何向前发展?那位美国分析师概述了两条路径:“要么Flutter需要开始在预测市场中抢占份额——也许作为做市商而非通过交易所——要么投资者需要对预测市场不会成为严重的长期逆风抱有信心。”
Flutter在2025年底通过与芝商所的交易所合作推出了FanDuel Predicts,起步比DraftKings的产品更为低调。从风险中获利,而不仅仅是提供平台,可能是使预测市场盈利而非仅具防御性的关键。
若做不到这一点,行业就只能等待法院裁决,而结果仍不确定。Robinson指出,内华达州成功限制了Kalshi,但第三巡回法院在新泽西州一案中裁定Kalshi胜诉,“目前没有具有约束力的全国性答案”。而且双方力量并不均衡:“内华达在商业上的重要性低于加利福尼亚、德克萨斯和佛罗里达,而核心威胁在这些州依然完好。”
那位美国分析师预计一切最终将上诉至最高法院,最终答案“最早也要到2027年底,更可能在2028年上半年”。在那之前,“这些股票存在横盘交易的风险”。
还有一个很少被讨论的担忧:如果法院最终阻止体育预测合约,投资于这些合约的公司“肯定会希望自己不会因参与其中而受到州议员的惩罚”,他说。“如果监管机构认定这些公司站在了问题的错误一边,它们可能不会那么容易被重新接纳。”
纽约能否带来Flutter承诺的收益?
这一切都没有削弱跨大西洋的吸引力。Allwyn——新近与希腊OPAP合并,在雅典上市,并通过PrizePicks进军美国——正在权衡在伦敦或纽约第二上市。
那位美国分析师将其解读为“有点套利操作的意味”,并补充说,“你在一个更小的市场中成为大得多的参与者——小池塘里的大鱼”。
Beynon否认上市地点之间存在竞争:“我们不认为上市博彩公司的投资是一场‘零和游戏’。”而那位美国分析师坚持认为Flutter的目的地是正确的:“我仍然认为美国是资本市场的黄金标准。”
Robinson的结论更为微妙。“直觉上觉得为时过早,但数学上可能支持这一决定,”他在谈到完全退出时说——尽管他也察觉到“时机选择中也有某种信息传递的意味:伦敦翻倍……